RA-IR-2026-002 · Reference release 01 · 27 September 2026
General Reconciliation: Proposal and Hold
The proposed register promised a clean account of unsettled records. Its rehearsal shows exactly what that account would lose. The last pages contain a signed decision and a separate disposition entry.
Reference deskReference copy available.
Begin with the short service file, or open the Working Record already kept by this browser.
The current record sequence contains contradictory office instructions and unassigned custodial consequences. The Working Group proposes a controlled register that would reduce duplicate descriptions to one current account, while preserving a citation to the retired version.
The proposed authority is administrative: where an account has no acknowledgement or recognized independent retention, the controlling register may mark it superseded. The draft treats absence of an entered return as absence of a continuing outside account.
Condition in proposal
Proposed treatment
Acknowledged office copy
Carry into the controlling register
Outside account with recognized retention
Preserve separately and cite its disposition
Account without acknowledgement or recognized independent retention
Eligible for supersession by the controlling register
Proposal only. The clause concerning an outside account is repeated precisely in the later review.
Records rehearsal; no operative apparatus used. The Working Group transcribed source descriptions into a proposed consolidated register and compared the output to the released records. No tray, volume or service procedure was operated in this exercise.
Source description before
Condensed draft after
12 and 19 October service entries kept separately
One combined service discrepancy
Witnessed procedure and ordinary desk comparison both retained
Observed irregular order retained; ordinary comparison omitted
The draft preserves that the unusual order was observed. It removes the control needed to distinguish a timed irregularity from ordinary desk movement.
Working copy; proposed fields, not an adopted register.
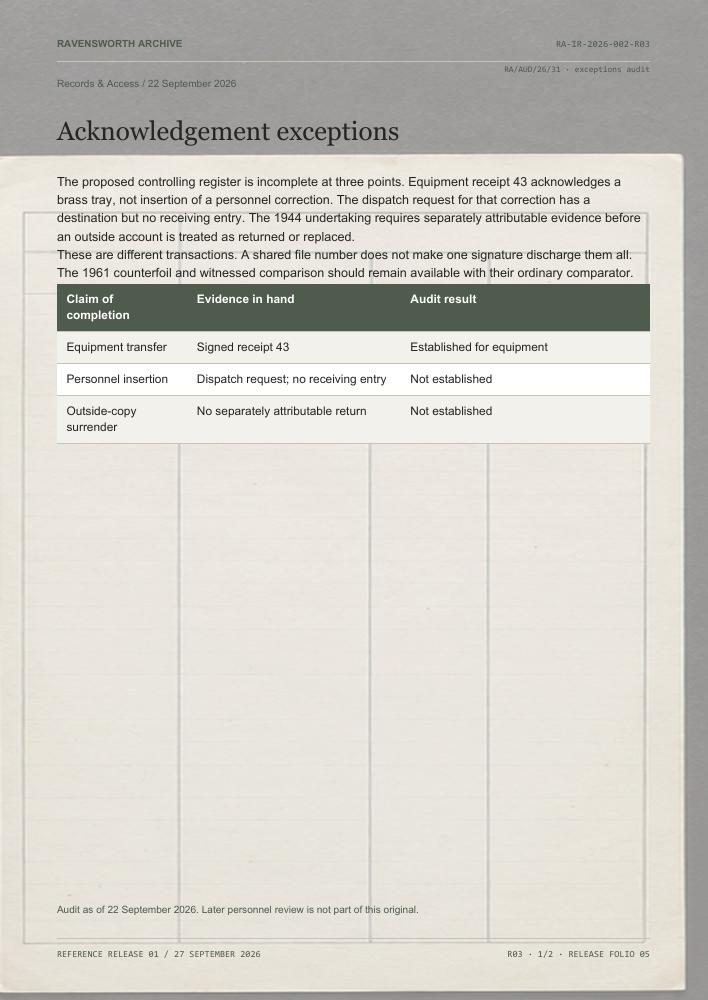
The proposed controlling register is incomplete at three points. Equipment receipt 43 acknowledges a brass tray, not insertion of a personnel correction. The dispatch request for that correction has a destination but no receiving entry. The 1944 undertaking requires separately attributable evidence before an outside account is treated as returned or replaced.
These are different transactions. A shared file number does not make one signature discharge them all. The 1961 counterfoil and witnessed comparison should remain available with their ordinary comparator.
Claim of completion
Evidence in hand
Audit result
Equipment transfer
Signed receipt 43
Established for equipment
Personnel insertion
Dispatch request; no receiving entry
Not established
Outside-copy surrender
No separately attributable return
Not established
Audit as of 22 September 2026. Later personnel review is not part of this original.
The General Reconciliation proposal of 15 September 2026 is held. Its consolidation authority is not established by the acknowledgements it relies upon. The 18 September rehearsal demonstrates that the proposed register would omit the ordinary comparison and treat an unacknowledged personnel insertion as closed.
Under the custodial undertaking accepted on 20 June 1944, an outside account cannot be deemed returned or superseded merely by changing the office register. Unreturned independent reference copies are not deemed surrendered. A personnel exoneration entered after source review may not be automatically superseded by this process.
Records & Access will retain the 1961 ordinary comparison, the equipment and correspondence distinction, and the reviewed personnel finding as separately citable descriptions. This determination takes effect on signature; the proposal has no standing as a replacement register.
M. Avery · Head of Records & Access · signed and entered 27 September 2026
Executed institutional hold. No reader action is required for it to take effect.
The ordinary comparison should accompany any description of the North Reading Room entry. Receipt 43 records the withdrawal of a brass tray; it cannot fill a blank acknowledgement for a personnel enclosure or dispose of a separately held copy.
A copy may remain in service after the equipment has been withdrawn. Our section has seen descriptions acquire further references after transfer between offices. I reserve the possibility that a sufficiently full description reproduces a relationship beyond its originating office. That is an operational concern offered for review, not a demonstrated rule in every collection.
The proposal should therefore be held until outside accounts, office custody and personnel corrections have separate dispositions. A shorter register may be easier to administer; ease does not make its missing fields true.
L. Carden · Collections & Custody · 23 September 2026
Retained departmental carbon. The author's operational theory is not an institutional finding.
Retained as independently attributable; no deemed surrender
TS/44/20
Personnel correction
Preserved; no automatic supersession
RA/PR/2026-09
Enclosure IX
Retained in administrative use; not in public packet
REC/61/IX-S
Return of an independent reference copy is not a condition of this finding. The signed hold was entered before preparation of this public schedule. An unreturned copy remains an outstanding account, not a consent to the proposed register.
N. Greer · Records & Access · entry checked by M. Avery · 27 September 2026
The consolidation authority is not established by its acknowledgements. Unreturned independent reference copies are not deemed surrendered, and personnel exonerations may not be automatically superseded by this process.
The decision resolves the proposed policy, not the general cause of the 1961 service order or every operational theory in the holdings.